RexMont
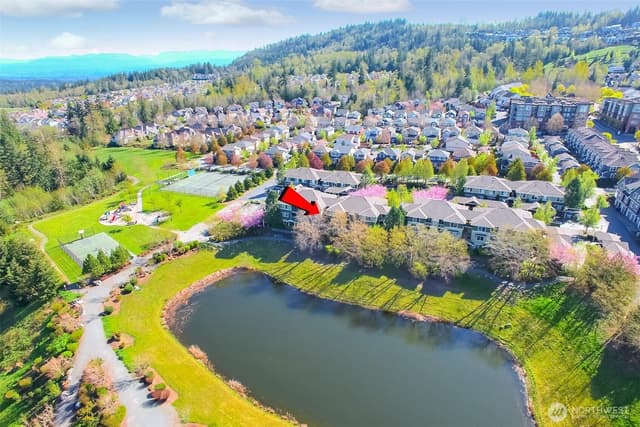
First-time home buyers reviewing an Issaquah Highlands neighborhood map with their agent

First-Time Home Buyer in Issaquah: The Program, Rate and Offer Playbook

Issaquah is one of the Eastside's most workable first-home markets, built on Highlands and Talus townhomes and condos. Here is today's rate, the WSHFC and ARCH programs that put money toward your down payment, the offer terms that win, and the homes live right now under the townhome median.

30-year fixed today
7.40%
Freddie Mac PMMS, week ending October 15, 2026
Live now under $799K
74
Active and contingent Issaquah listings on NWMLS, refreshed through the day
Brokerage proof
1,242 Google reviews, 5.0 average, 1,200+ closed transactions

By the numbers

Production behind the marketing

First purchases in Issaquah get the same brokerage behind them as every RexMont transaction: real closed production, a concierge team, and the most-reviewed record in the region.

$1B+
Closed in production
1,200+
Transactions closed
1,242
5-star Google reviews
5.0
Average client rating
Adriano Tori, Designated Broker — RexMont Real Estate

Page author

Adriano Tori

Founder & Designated Broker — RexMont Real Estate · WA Lic. #27660

Adriano Tori wrote and reviews this Issaquah first-time buyer guide. He has guided first purchases across Seattle and the Eastside through every rate environment since RexMont opened, and he supervises every RexMont buyer's agent.

5.0 · 1,242 Google reviewsBest of 2026NWMLS MemberAbout Adriano →

Answer first · reviewed 2026-10-18

A first-time buyer in Issaquah can buy with 3% down, and two layers of assistance stack on top: Washington State Housing Finance Commission programs (Home Advantage, open to households earning up to $215,000 with no first-time requirement, and House Key Opportunity for first-time buyers) and ARCH East King County's deferred second mortgage of up to $30,000 for homes under its price limits, since Issaquah is an ARCH member city. The realistic entry is condos and townhomes in the Issaquah Highlands, Talus and central Issaquah. RexMont buyer's agents set the lender, the ceiling and the two-association HOA review before the first tour.

Mortgage basics

What a first Issaquah home costs each month at today's rate.

The example below uses the current 30-year fixed survey rate (7.40%, Freddie Mac PMMS, week ending October 15, 2026) and a purchase at $799,000, which is the current Issaquah townhome median list price (figure as of 2026-10-01). It shows principal and interest only. Property tax, homeowner's insurance, any HOA dues, and mortgage insurance on loans with less than 20% down sit on top, and your lender's quote will differ from a national survey average.

Down paymentCash downLoan amountPrincipal and interest / month
3%$23,970$775,030$5,366
5%$39,950$759,050$5,256
10%$79,900$719,100$4,979
20%$159,800$639,200$4,426

Illustration only, not a loan offer. Rate source: Freddie Mac Primary Mortgage Market Survey via FRED, refreshed daily. 3% down reflects conventional first-time buyer programs; 3.5% is the FHA minimum.

Pre-approval, not pre-qualification

A Issaquah listing agent reads the lender letter before the price. Ask your lender for a fully underwritten pre-approval with income, assets and credit already reviewed, so the only open item at offer time is the appraisal.

Debt-to-income is the real ceiling

Most conventional loans cap total monthly debt near 43% to 50% of gross income depending on the file. Student loans, a car payment and HOA dues all count. Pay down the smallest revolving balances first; they move the ratio fastest.

Rate locks and buy-downs

Locks typically run 30 to 60 days. In a slower segment a seller credit can fund a temporary or permanent rate buy-down, which often lowers the payment more than the same dollars off the price. Your agent writes that into the offer.

Run your own numbers

Pre-loaded with today's survey rates. Change the price, down payment and term to match the homes you are watching.

Home price

$

Loan amount: $680,000 · LTV: 80.0%

Down payment

%
$170,000

Loan term

Interest rate

%
Freddie Mac PMMS · Oct 15, 2026:

Monthly cost estimates

$
/mo

King County estimate · 0.9%/yr

$
/mo
$
/mo
$
/mo

Estimated monthly payment

$5,495

Principal & Interest$4,708
Property Tax$637
Homeowners Insurance$150
HOA Dues$0
Mortgage Insurance$0
Loan amount$680,000
LTV ratio80.0%
30-yr total interest paid$1,014,946
Get a real lender quote →

Estimates only — not a lender quote. P&I from standard amortization. Property tax uses King County 0.9% annual estimate; verify with the King County Assessor. PMI estimate assumes conventional coverage and drops at 20% equity. FHA and VA loans have different insurance structures.

Down-payment programs

First-time home buyer programs that work in Issaquah.

The Washington State Housing Finance Commission (WSHFC) does not lend directly; it sets the programs and a network of Commission-trained lenders originates the loans. Every Commission first mortgage can carry downpayment assistance, structured as a second mortgage with payments deferred until you sell, refinance or move out. The Commission reports $15,000 as the typical assistance amount and second-mortgage rates from 0% to 4% depending on the program. The required homebuyer education class is free, runs about five hours, and the certificate is valid for two years.

Statewide · WSHFC

Home Advantage

The Commission's main first-mortgage program. You do not have to be a first-time buyer, and every Home Advantage loan can carry downpayment assistance.

  • Household income up to $215,000, statewide, regardless of household size
  • Commission-sponsored homebuyer education class completed within the last two years
  • Home Advantage DPA: a 0% interest, payment-deferred second mortgage of 3%, 4% or 5% of the first-mortgage amount, repaid when you sell, refinance, transfer or stop living in the home
Program details at the Commission →

Statewide · WSHFC

House Key Opportunity

A below-market first mortgage reserved for first-time buyers, defined as anyone who has not owned and occupied a primary residence in the past three years, or buyers purchasing in a designated Target Area.

  • Income limits set by county and household size; King County is $93,350 for one or two people and $116,650 for three or more
  • Same homebuyer education requirement; the certificate is valid for two years
  • Opportunity DPA: up to $15,000 at 1% simple interest, payment-deferred until sale, refinance or transfer
Program details at the Commission →

Statewide · WSHFC

Other Commission downpayment programs

Several targeted second mortgages stack with a Commission first mortgage. Eligibility for each is set by the Commission, not by RexMont or your lender.

  • HomeChoice: up to $15,000 when the borrower or a household member has a verified disability
  • Veterans Downpayment Assistance: up to $10,000 for eligible veterans
  • Covenant Homeownership Program: a state program with its own eligibility rules, described at heretohome.org
Program details at the Commission →

Issaquah area

ARCH East King County downpayment assistance

A Regional Coalition for Housing (ARCH) funds a deferred second mortgage for buyers in its member cities, Issaquah among them, alongside Bellevue, Redmond, Sammamish, Kirkland, Bothell and the other Eastside members. It is administered through the Commission's lender network.

  • Up to $30,000 at 4% simple interest, payment-deferred until sale, refinance, transfer or payoff
  • No first-time requirement; the home must be owner-occupied and not rented in the prior 90 days
  • Purchase price limits of $646,000 for existing homes and $660,000 for new construction; income limits by household size from $81,700 to $154,000
  • Buyer contributes 2% of the price, half of which may be gift funds
Read the program page →

Issaquah area

Issaquah Highlands and Talus HOA review

Most Issaquah first purchases are condos and townhomes in the Highlands, Talus and central Issaquah, and many sit under two associations at once: a community-wide association and the building or townhome association. RexMont reads both resale certificates, both budgets and any pending special assessment before you write, and your lender confirms the building qualifies for the loan program.

  • Two sets of dues are common; both count in your debt-to-income ratio
  • Reserve funding and recent special assessments change your monthly number and your financing
  • Owner-occupancy ratios and litigation affect which loan programs a building qualifies for
Read the program page →

Program terms read from wshfc.org and heretohome.org on October 1, 2026. Income and price limits reset annually and vary by household size; confirm current figures with a Commission-trained lender before writing an offer. RexMont is a real estate brokerage, not a lender, and does not determine program eligibility.

Live NWMLS search

Issaquah homes for sale under $799K

Active and contingent Issaquah listings priced at or below $799,000, the current Issaquah townhome median list price. Pulled directly from NWMLS; the full search lets you add bedrooms, type and neighborhood.

Search every Issaquah home under $799K →
Median price
$442,000
Median $/sqft
$448
Avg days on market
51
Listings for sale
24+

Listing data courtesy of NWMLS. Provided for the consumer's personal, non-commercial use. Market stats are calculated from the active NWMLS listings shown here for Issaquah; individual neighborhoods and property types may vary.

Search every Issaquah home under $799K →

Information and statistics derived from Northwest Multiple Listing Service. Source: Northwest Multiple Listing Service, as distributed by MLS GRID.

Based on information submitted to the MLS GRID as of October 18, 2026 at 11:09 AM PT (date and time MLS GRID Data was obtained). All data is obtained from various sources and may not have been verified by broker or MLS GRID. Supplied Open House Information is subject to change without notice. All information should be independently reviewed and verified for accuracy. Properties may or may not be listed by the office/agent presenting the information.

Listing information courtesy of Northwest Multiple Listing Service (NWMLS). The listing data relating to real estate for sale on this web site comes in part from the Northwest Multiple Listing Service. Real estate listings held by brokerage firms other than RexMont Real Estate are marked with the “Listing courtesy of NWMLS” designation. Information provided is for the consumer’s personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.

Some IDX listings have been excluded from this website.

© 2026 Northwest Multiple Listing Service. All rights reserved. Listing information deemed reliable but not guaranteed.

Copyright concerns
Offer strategy

How first-time buyers win in Issaquah without overpaying.

Issaquahoffers are won on terms and certainty as much as price. These are the levers a RexMont buyer's agent sets with you before the first tour, so the decision on offer night is already made.

Step 1

Price both association budgets before the house

In the Highlands and Talus the monthly cost is the mortgage plus two sets of dues. Add both before you set a ceiling, so the price you write is one you can carry, not one that looked right before the resale certificates arrived.

Step 2

Set the ceiling from the payment, not the comps alone

Decide the monthly number you can carry with dues, taxes and insurance included, convert that to a price ceiling, and write the escalation cap from it. The cap stays fixed when a well-priced Highlands townhome draws a crowd.

Step 3

Ask for the credit where the segment is slower

Issaquah townhomes and condos typically sit on the market longer than detached homes. On those, a closing-cost credit or a rate buy-down lowers your payment more than the same dollars off price, and sellers accept it more readily than a cut to the headline number.

Step 4

Read the building before you read the finishes

On a condo the inspection is mostly the association: reserve study, minutes, pending assessments. On a townhome, confirm whether the roof, siding and decks are the owner's or the association's before you set the inspection window.

Step 5

Get the lender in front of the listing agent early

A fully underwritten pre-approval from a lender who closes Eastside condos and Commission program loans, plus a call to the listing agent before the review date, removes the doubt that sinks first-time offers.

Step 6

Compete on certainty

Earnest money of 2% to 3%, a close date that matches the seller's move, and clean contingencies with short windows beat a marginally higher price with more risk. Your buyer broker compensation is set in your buyer services agreement and can be requested from the seller in the offer.

First-time buyer FAQ

Questions first-time buyers in Issaquah ask before they start.

What first time home buyer programs are available in Issaquah?

Three layers apply in Issaquah. Statewide, the Washington State Housing Finance Commission offers Home Advantage (no first-time requirement, household income up to $215,000, 0% deferred downpayment assistance of 3% to 5% of the loan) and House Key Opportunity (first-time buyers, King County income limits, up to $15,000 at 1% deferred). Locally, Issaquah is an ARCH member city, so ARCH East King County adds up to $30,000 at 4% simple interest for homes priced up to $646,000 existing or $660,000 new. A Commission-trained lender confirms the combination.

Can a first-time buyer realistically buy in Issaquah?

Yes, and more easily than in most of the Eastside. Issaquah has a deep supply of condos and townhomes in the Highlands, Talus and central Issaquah, and condos there often list under the ARCH price limits. The live feed on this page shows what is active under the Issaquah townhome median right now.

How much down payment do I need for an Issaquah home?

Conventional first-time buyer loans start at 3% down and FHA at 3.5%; WSHFC and ARCH assistance can cover part of that as a deferred second mortgage. Above the conforming loan limit you are in jumbo territory, where lenders typically want 10% to 20% down, so most first purchases in Issaquah stay in the condo and townhome range where conforming loans apply.

Why do some Issaquah homes have two HOA dues?

Master-planned communities like the Issaquah Highlands have a community-wide association for parks, trails and common areas, and many condo and townhome buildings have their own association on top. Both dues are part of your monthly cost and both count in your debt-to-income ratio, so RexMont reviews both budgets before you write.

Who counts as a first-time home buyer in Washington?

For Commission programs, anyone who has not owned and occupied a primary residence in the past three years. Home Advantage and ARCH have no first-time requirement at all, so a buyer who sold years ago or who owns elsewhere can still qualify.

What does a buyer's agent cost a first-time buyer in Issaquah?

The fee is stated in the buyer services agreement you sign before touring and is negotiable. Your offer can ask the seller to pay some or all of it, and sellers commonly agree, so many first-time buyers pay nothing out of pocket for representation.

First-home alerts

Get Issaquah homes in your budget the hour they list.

Set your ceiling, bedrooms and timeline. A RexMont Issaquah agent reviews every match before it reaches you, flags the ones where a program or a seller credit changes the math, and arranges private tours.

$

One daily email at most when new homes match. Pause or unsubscribe any time. We never share your information.