Market Insights
What the rate hike did to a Seattle mortgage payment (as told on Fox 13)
September 25, 2026 · 5 min read

By Adriano Tori
Founder & Designated Broker, RexMont Real Estate
WA Lic. #27660
Seattle & Eastside Real Estate Market Strategist
★ BusinessRate Best of 2026 Award Winner
★★★★★ 1,241 Google reviews · Seattle and the Eastside's most-reviewed brokerage
Freddie Mac printed the 30-year at 7.03% at 9:00 AM on September 24. Twenty minutes later I was on Good Day Seattle explaining what that did to the payment on a typical Seattle house. Here is the math, the sources, and what a frozen market means if you own or want to buy.
Live market snapshot
Seattle real estate — right now
- Median price
- $935K
- Avg days on market
- 53
- Active listings
- 270
- Months of supply
- 3.9
30-yr fixed today: 7.03%
Source: MLS GRID / NWMLS market data · zip 98103 · 30-yr rate: Freddie Mac PMMS via FRED. Educational only — confirm with a licensed agent.
The number that posted twenty minutes before air
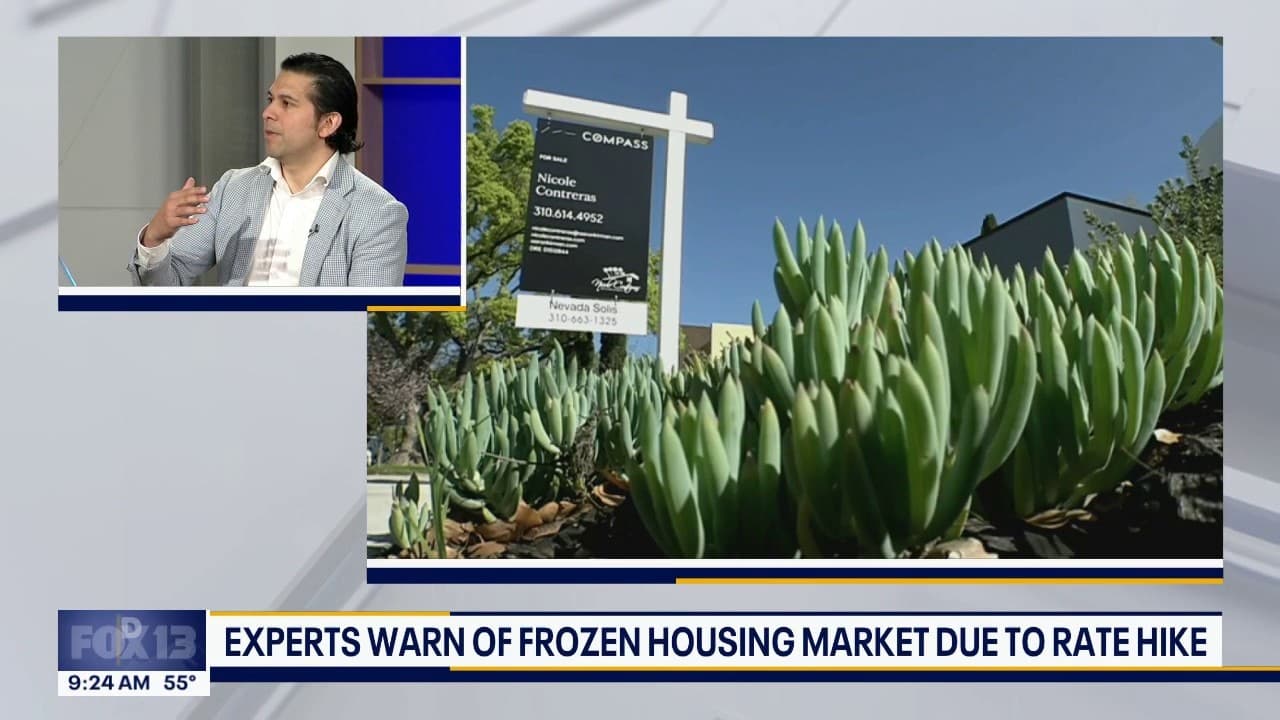
Freddie Mac publishes its weekly 30-year fixed average every Thursday at 9:00 AM Pacific. On September 24 it printed 7.03%, up from 6.95% the week before and 6.76% the week before that. My segment on Fox 13 Good Day Seattle started at 9:20, so the first thing I did on air was read the new number. You can watch the segment on the station's site: Experts warn of frozen housing market due to rate hike.
The chain of events is short. The 10-year Treasury touched 5% on September 14 for the first time since 2023. The Fed raised a quarter point on September 16, its first hike since 2023. Mortgage rates follow the bond market, not the Fed directly, which is why they moved first and kept moving.
What it costs on a typical Seattle house
The Seattle single-family median list price on our Seattle housing market page is $944,000 this month. Put 20% down and you are borrowing $755,200. On a 30-year fixed, principal and interest only, that loan costs about $4,518 a month at February's 5.98% low, $4,999 at last week's 6.95%, and $5,040 at the 7.03% that printed this morning.
That is roughly $40 more a month than a week ago and about $520 more than in February, on a house that did not change. Over the first five years of the loan the February-to-now gap is more than $31,000. That is the whole story of the segment in one line: the house is the same, the payment is not.
The rates are Freddie Mac's and the Fed's numbers. The house price is ours, pulled from active Seattle listings and refreshed the first week of every month with the property types split apart: houses at $944K and 29 days on market, condos at $548K and 58 days, townhouses at $771K and 47 days.
Why the market froze instead of falling
Most owners in Seattle hold a mortgage written between 2019 and 2022 at rates between 2.5% and 4%. Selling means giving that rate up and financing the next house at 7%. So they do not list unless a job, a divorce, a baby or a death forces the move. That is the freeze the Fox 13 headline refers to: not a crash in prices, a collapse in transactions.
You can see it in the days-on-market split. Seattle overall sits at 44 days, but single-family homes move in 29 while condos take 58. The few houses that list still find buyers who have been waiting all year. Condos, where the payment math bites hardest for first-time buyers, are the segment that stalls.
Prices in a freeze drift rather than drop. Sellers who priced in June are quietly accepting offers a few percent under list; sellers who priced this month are pricing to the new payment from day one. Neither shows up as a headline decline.
If you own a Seattle home and were thinking about selling
A frozen market punishes sellers who price to spring and reward sellers who price to the buyer's payment. Before you list, ask what your house costs a buyer per month at 7%, not what the neighbor got in April. Our home value page runs that number for you, and a listing that clears the buyer's payment test on day one is the one that sells in 29 days instead of 90.
If you are moving up, the rate you give up matters less than people think when the next house is bought in the same market. You lose the low rate on a $900K house and gain negotiating leverage on a $1.4M one where the seller has been sitting for two months. Run both sides of the trade, not one.
If you are buying
Seven percent is not the end of the conversation, it is the start of the negotiation. Fewer buyers are qualifying at this payment, so the buyers who are still in the market have leverage they did not have a year ago: seller-paid rate buydowns, closing-cost credits, and inspection repairs are back on the table in Seattle for the first time since 2019.
Get pre-approved at today's rate with the buydown priced in, decide the monthly payment you will live with, and shop houses that have been listed more than 30 days. That is where the credits are. If rates fall next year you refinance; if they do not, you bought a house at a price that already reflected 7%.
Where every number in the segment comes from
Every figure I used on air is on a public page that a producer, a reporter or a buyer can check in thirty seconds. The Seattle numbers are on our Seattle housing market report. The county view, which links to all 25 King County city reports, is the King County housing market hub. We rebuild all 47 Puget Sound city reports on the same methodology the first week of every month, and every page shows the date it was last refreshed.
Rates are from Freddie Mac's Primary Mortgage Market Survey, published each Thursday. The Fed decision and the 10-year Treasury move are from the Federal Reserve and the Treasury market. Nothing in the segment was a forecast; it was what the numbers said that morning.
Frequently asked questions
- What is the mortgage rate in Seattle right now?
- Freddie Mac's national 30-year fixed average printed at 7.03% on September 24, 2026. Seattle-area quotes track that number closely, with jumbo loans above the conforming limit often pricing slightly differently. Your rate depends on credit, down payment and whether the seller contributes to a buydown.
- How much is the monthly payment on a $944,000 Seattle house?
- With 20% down and a 30-year fixed at 7.03%, principal and interest is about $5,040 a month. At 6.95% it was $4,999, and at February's 5.98% it was $4,518. Taxes, insurance and any HOA dues are on top of that.
- Will Seattle home prices fall because of the rate hike?
- The pattern so far is a freeze, not a fall. Owners with low-rate mortgages are not listing, so inventory stays tight and prices drift rather than drop. Individual sellers who priced before the hike are accepting a few percent under list; new listings are pricing to the new payment from the start.
- Is it a bad time to buy in Seattle at 7%?
- It is a better time to negotiate than any point since 2019. Seller-paid rate buydowns, closing credits and repairs are back, especially on homes listed more than 30 days. Buy the house at a price that reflects 7% and refinance if rates fall.
Explore related pages
Talk to RexMont
Get a strategy session before you move.
RexMont is Seattle and the Eastside's most-reviewed brokerage — 1,241 five-star Google reviews, $1B+ closed. Our agents pair live market data with honest pricing, offer strategy, and negotiation guidance built for Seattle, Bellevue, and the Eastside.
BusinessRate Best of 2026 Award Winner: Real Estate Agent, Bellevue, Washington. Sell with an award-recognized Bellevue real estate agent backed by local client reviews.
Forms and calls go to a live agent — expect a response within minutes during business hours.
Local guide: Seattle real estate agents
Sources & references: Northwest Multiple Listing Service (NWMLS), Federal Reserve Economic Data (FRED), Federal Housing Finance Agency (FHFA), National Association of Realtors (NAR), Washington State Department of Revenue (REET schedules), King County Assessor, Bellevue / Kirkland / Redmond / Seattle municipal permit and zoning portals, Washington State Housing Finance Commission (WSHFC), and RexMont Real Estate in-house transaction data. Statistics, rates, and figures referenced are accurate as of publication and may change. Information is provided for educational purposes and is not legal, tax, financial, or investment advice.